
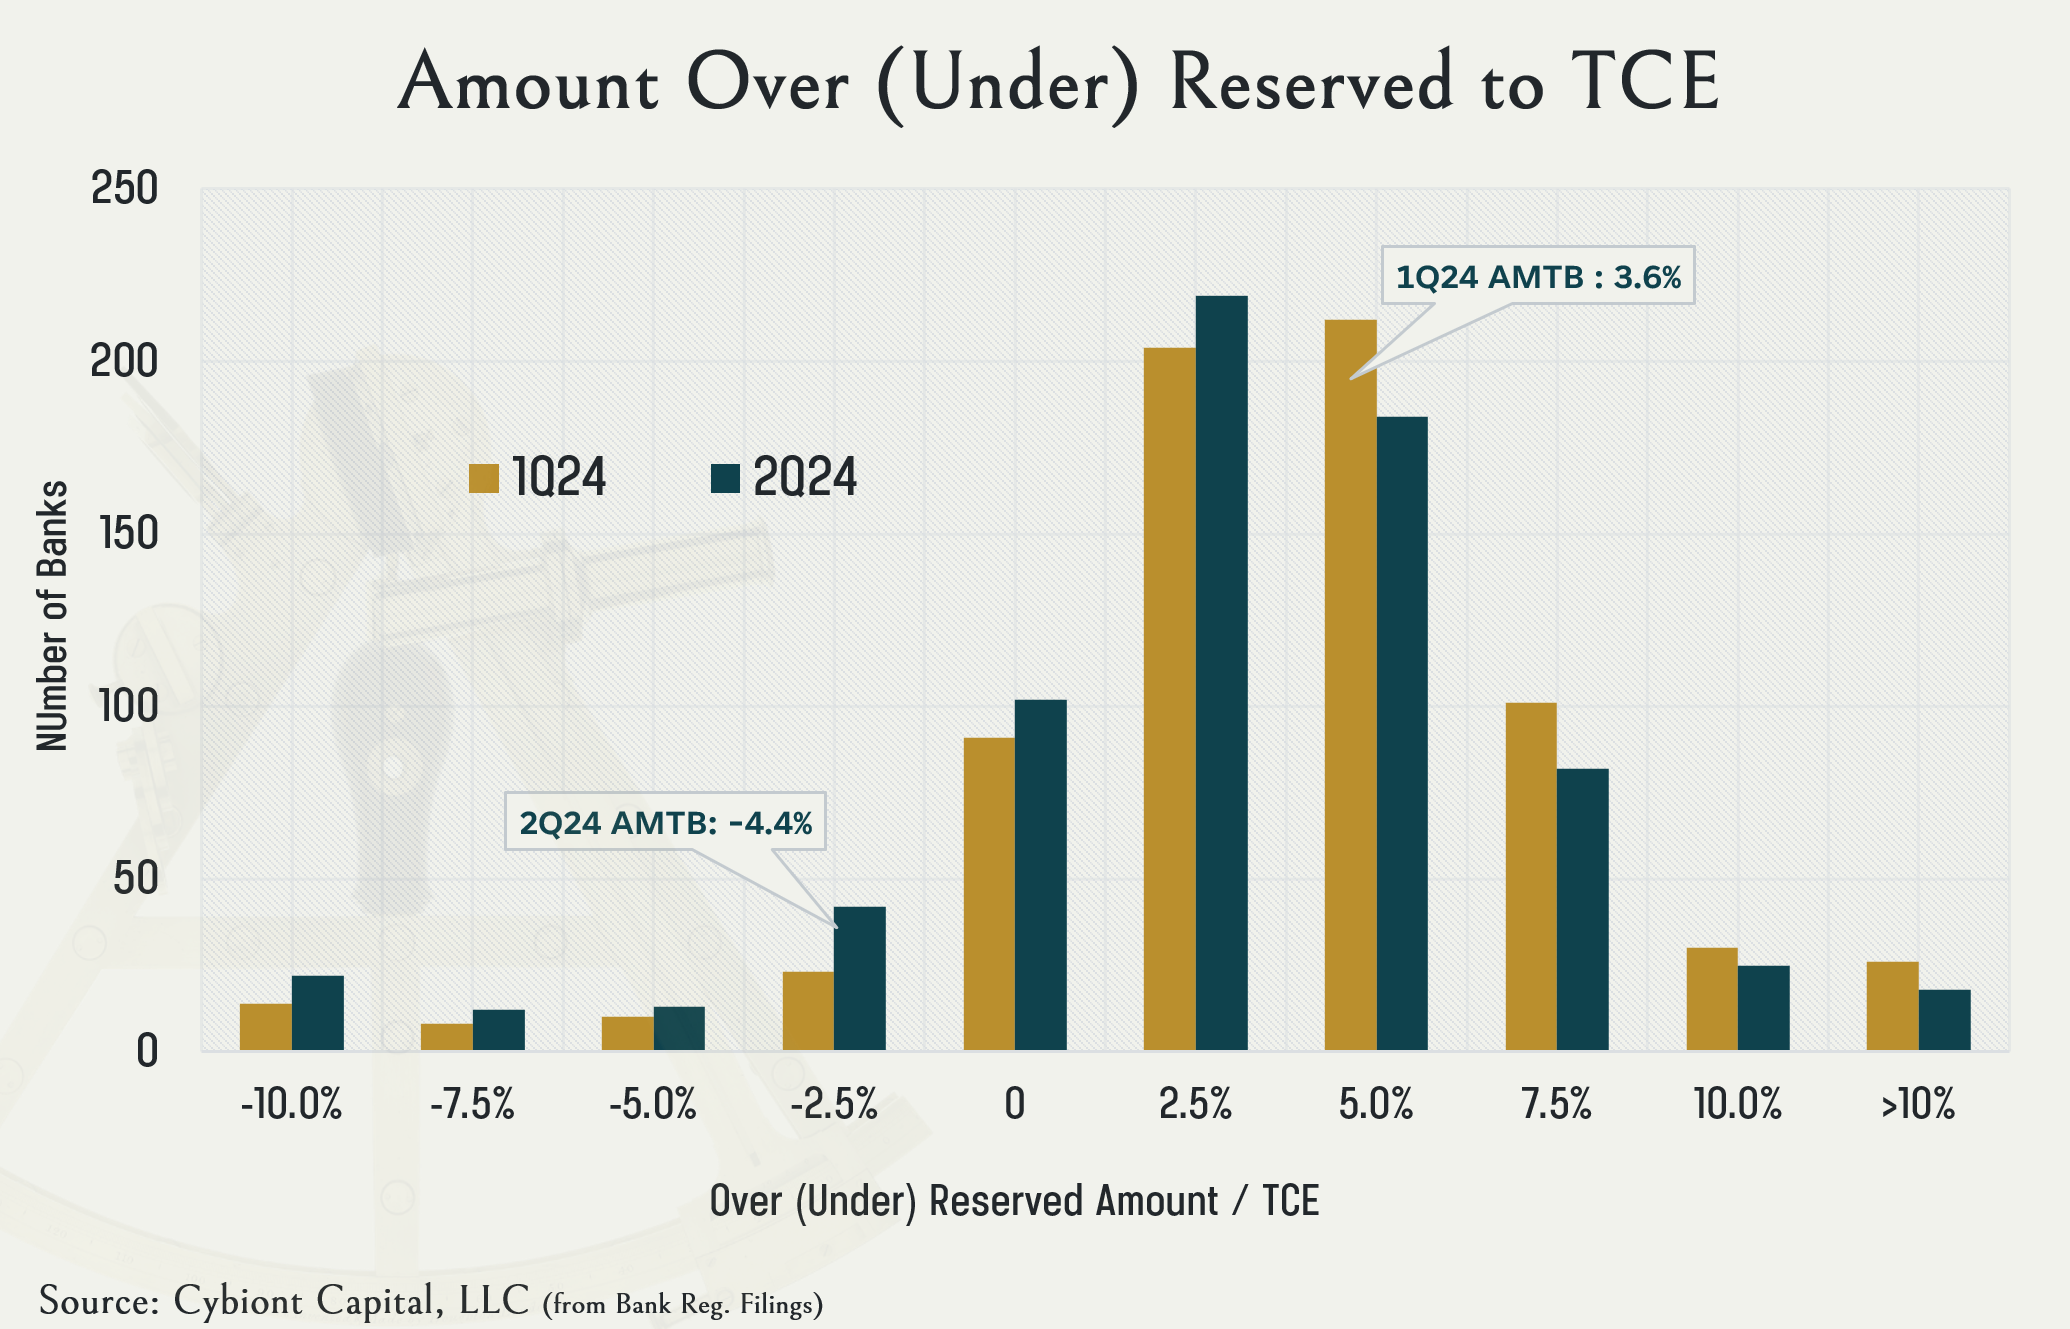
Following the release of Cybiont’s 2Q24 Reserve Adequacy Modeling Report, we received several requests to walk through an example explaining the circumstances that might cause a bank to move within the distribution.
The chart below shows our modeled distribution of reserve adequacy for covered banks. AMTB is among the banks whose position in the distribution changed significantly Q-on-Q. For the 1Q24 analysis, we modeled that AMTB was over-reserved by about 3.6% of the bank’s tangible common equity (TCE) or about $26 million. As of 2Q24, we model that the bank is about $31 million under-reserved, or about 4.4% of TCE.1

These factors that determine our reserve expectations include the following quantifications:
- Determining required reserves under CECL (current expected credit losses) for the performing book by loan type based on “through-the-cycle” expected losses,
- Assessing historical industry loss rates for each loan type that are then tempered by each bank’s historical loss experience,
- Analyzing the stock and development rate (flow) of underperforming loans and OREO to which we apply a default probability and loss given default,
- And when conditions warrant, closely monitoring banks’ Cybiont “C” scores to estimate distance to a capital raise or regulatory intervention.
During 2Q24, AMTB placed nearly $27 million and over $28 million in C&I and owner-occupied ComRe, respectively, on nonaccrual, which caused their underperforming formation rate to increase to about 8% for these loan categories, up from 0% formation in the previous quarter. Formation of underperforming loans is among the most significant factors determining our expectations for reserve levels.
While the bank indicated that the increase was attributable to “a few large loans,” our experience, and therefore our modeling, assumes that the trend in asset quality is likely to continue in the near term. Moreover, AMTB increased its provision expense only slightly from the previous quarter and didn’t even cover charge-offs during the quarter, thus, depleting the reserve marginally.
Should AMTB’s credit quality trend reverse in upcoming quarters, our model will credit the bank for the reversal. But for now, we view the bank as under reserved and equity as overstated.
- We have not spoken to AMTB, nor do we hold a position in the bank. Moreover, we have no additional insight into the bank’s reserving methodology or whether better nonpublic data would change our opinion of its reserve adequacy. ↩︎


Leave a Reply