
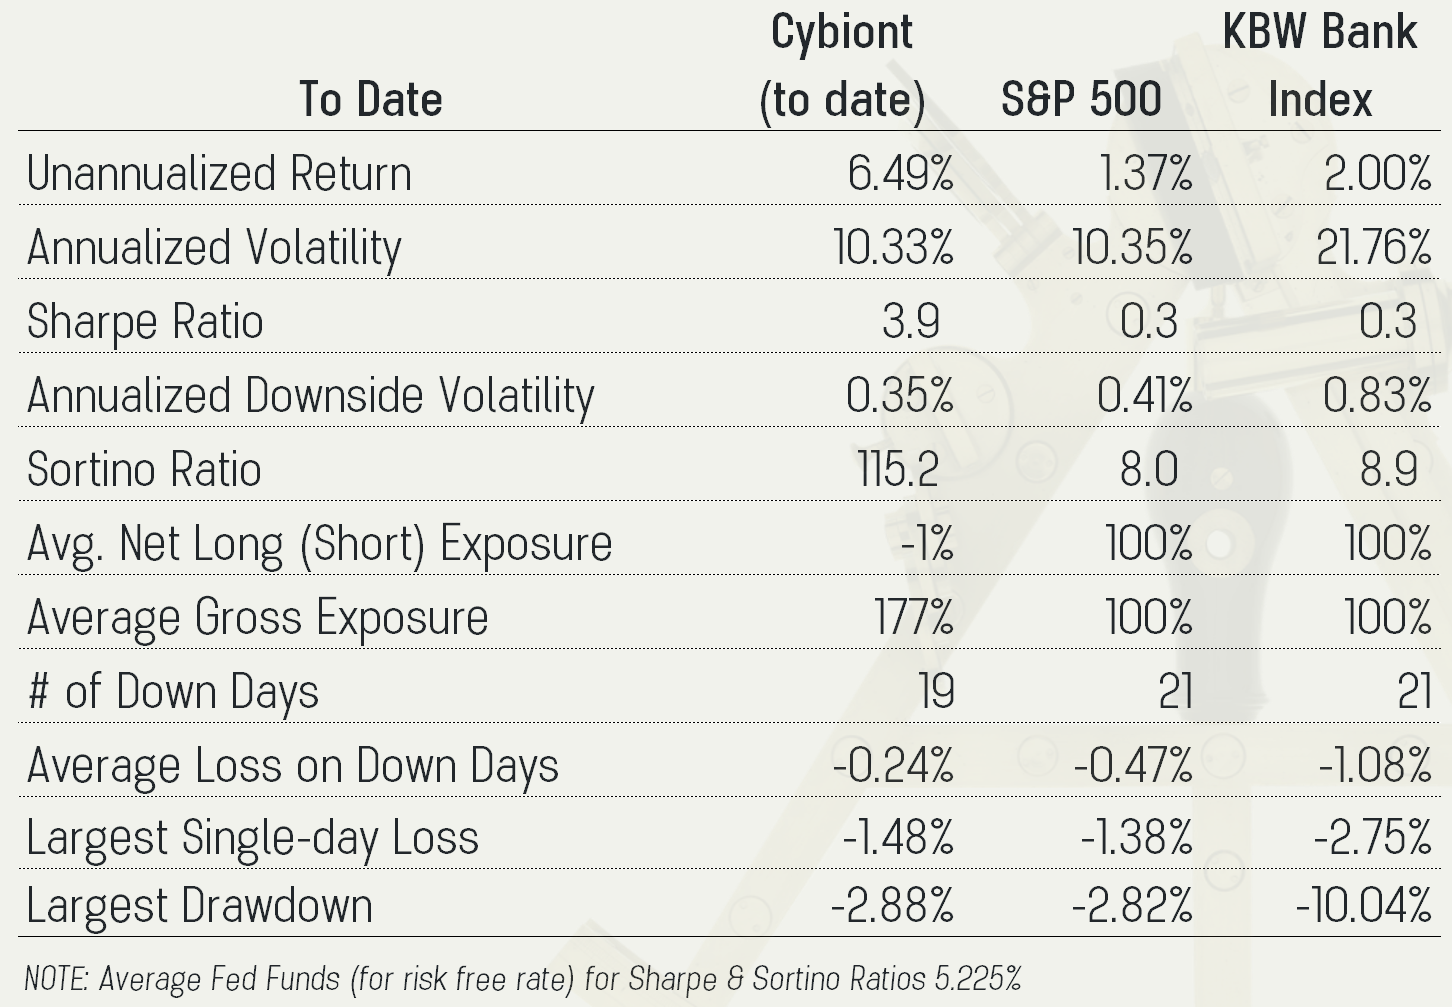
Beginning in July 2023, we are publishing our returns from our $ neutral Long/Short Systematic Portfolio.1
We believe that the reporting of earnings is our best catalyst for performance. As banks report, it either validates our modeling of the industry’s risks and opportunities or it doesn’t. Accordingly, in the interim between earning seasons, we bring the fund’s gross exposure down to protect our performance from idiosyncratic catalysts; such as an acquisition of a short or an unfavorable regulatory event for a long. For August we brought our gross exposure down from an average of 214% of NAV in July to 166% in August.
Reflecting our overall view that near-term prospects for banks will disappoint analysts’ expectations for Net Interest Income (See Net Interest: Rising Beta, August 25, 2023), we moved to an average Net Short Exposure of 5% in August from July’s Net Long exposure of 1%.
August Performance
While 0ur returns were muted for August (roughly break-even), it compared very favorably to the annualized -68% loss for the KBW Bank Index. Our Sharpe Ratio was negative for month given our underperformance to the risk-free rate, which averaged 5.33% for the month. Our volatility, as targeted, remains lower than the various broader indexes as well as the fund’s level during earnings season. Annualized volatility was 10.39% in August, compared to KBW Bank Index’s 17.48% and our fund’s 11.75% annual vol in July.

To Date Performance
We’re pleased with out performance to-date (recognizing that a 2-month return isn’t much of a trend). Our strategy of avoiding downside risk paid off this month as the BKX lost a significant portion of the gain it enjoyed in July. We’re thrilled with our nearly 46% annual return to date (compared to the BKX’s almost 13% annualized return for the two months); and we are especially satisfied that we were able to accomplish this return with less than half the volatility of the BKX, which generated a Sharpe Ratio of almost 4. Given our protection of the downside, we generated a Sortino Ratio of 115.

As a reminder, the governing risk parameters of the fund are as follows:

From time to time we also take more concentrated positions in high conviction ideas; but that is NOT part of this portfolio or strategy. Instead, we are operating by what we define as “Quantimental” wherein we engage in quantitative strategies derived relative to proprietary fundamental variables that create markers for the risks and opportunities that our macro analysis tells us are in play in any given banking regime.
Cybiont’s Quantimental Approach

Nothing here is intended as an offer to sell, or a solicitation of an offer to buy the interests described herein. Such offer or solicitation may only be made to qualified offerees by means of a confidential private offering memorandum or confidential explanatory memorandum (each a “Memorandum”) which contains important information (including investment objective, policies, risk factors, fees, tax implications and relevant qualifications), and only in those jurisdictions where permitted by law. Interests in Cybiont Capital, LLC shall not be offered or sold in any jurisdiction in which such offer, solicitation or sale would be unlawful until the requirements of the laws of such jurisdiction have been satisfied.
Before making an investment decision with respect to the Funds, potential investors are advised to carefully read the Memorandum, the partnership agreement of the Funds and the related subscription agreement, and to consult with their tax, legal and financial advisors.
An investment in the Funds is speculative and involves a high degree of risk. Opportunities for withdrawal and transferability of interests are restricted. There is no secondary market for the interests, and none is expected to develop. Leverage may be employed in the portfolio, which can make investment performance volatile. An investor should not make an investment unless it is prepared to lose its entire investment. The fees and expenses charged in connection with this investment may be higher than the fees and expenses of other investment alternatives and may offset profits.
- Investment Philosophy in Brief: This is a rules-driven $ neutral long/short fund using US Bank stocks to provide uncorrelated strong absolute returns with low volatility. As such, we do not consider the KBW Bank Index (BKX) to be a relevant benchmark. Were we to endeavor to benchmark the BKX, we would not run close to $ neutral, and we would incur higher volatility.This portfolio is managed according to the principles set out in Cybiont’s Investment Philosophy & Process. ↩︎


Leave a Reply